Updated 7 days ago
This content is sponsored by Scotiabank. The views, opinions, and information expressed in this piece are those of Moving2Canada and do not reflect those of Scotiabank. Scotiabank is not responsible for the content, accuracy, or any representations made herein.
Navigating the Canadian financial landscape can be tough without the right information. In this article, we'll discuss the common financial mistakes newcomers should avoid in Canada.
Top Financial Mistakes Newcomers Make in Canada (Quick Summary)
| Mistake | How to avoid it |
|---|---|
| 1. Not planning your budget | Make a budget before you arrive and review it every six months |
| 2. Not building your credit score | Get a newcomer credit card and pay it on time |
| 3. Not maintaining good credit | Set up pre-authorized payments for your bills |
| 4. Not reading terms and conditions | Read every contract before you sign |
| 5. Carrying credit card debt | Pay your balance in full every month |
| 6. Not filing your taxes | File every year by April 30, even with no income |
| 7. Not budgeting for your move | Include shipping, visa fees and transfer costs |
| 8. Not asking questions | Talk to a financial advisor early |
1. Not Planning Your Budget
Budgeting is the first rule to financial success, whether you’re immigrating to Canada or anywhere. Even so, over 68% of Canadians lack a financial plan. Not having a budget might lead to unexpected financial setbacks, especially when settling into a new country.
Before arriving in Canada, choose one of the recommended budgeting methods for newcomers or create one that outlines the following:
- Your fixed costs (i.e. expenses you must pay regularly)
- Financial goals (e.g. buying a home with a First Home Savings Account, education, starting a business)
- Anticipated expenses (e.g. groceries, household items, fun and entertainment)
- Unanticipated expenses (a “rainy day” fund)
Regularly track your spending habits and adjust them to ensure your financial goals remain achievable.
After you establish your budget, be sure to review it every six months to align your goals with your new situation. For example, if you start making more money, you may wish to redistribute your earnings to meet new goals.
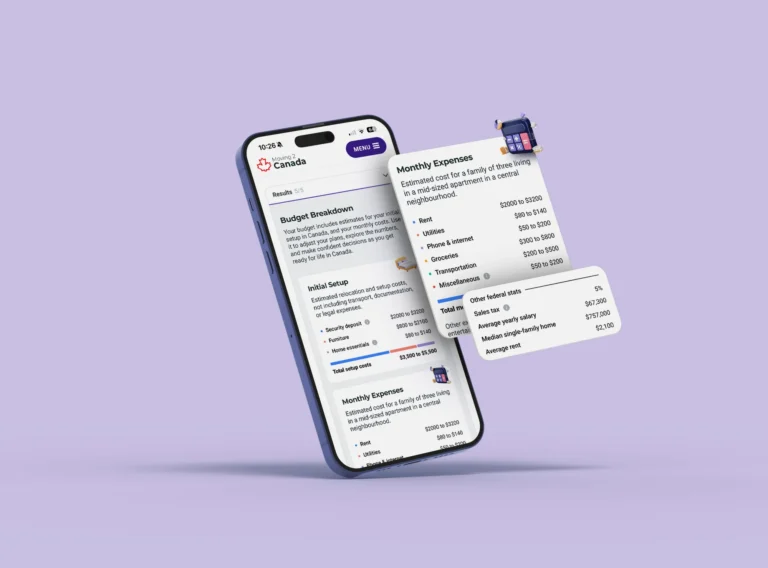
Want to get a head start on budgeting? Moving2Canada’s Budget Calculator is an interactive budgeting tool that helps you plan for Canada’s cost of living.
2. Overlooking the Importance of Building Your Credit Score
A good credit history is crucial in Canada, as it affects your access to financial services and interest rates.
Your credit history from your home country doesn’t transfer, so you start from zero, and lacking a credit history or having a poor one can be a barrier when applying for loans, insurance, or even cell phone plans.
One way to start building your credit history in Canada is with a credit card. Apply for credit cards that have newcomers in mind, such as the Scotiabank credit card for Newcomers. Paying off your credit card on time will gradually build a healthy credit score.
Canada’s two credit bureaus are Equifax and TransUnion. Banks, landlords, car dealers and phone companies use the reports from these bureaus to decide whether to approve you and on what terms. You can request your credit report from both for free, which helps you track your progress and spot any errors that could lower your score.
3. Not Maintaining a Good Credit History
Building credit is just the first step. After that, the trick is to maintain it. Your credit score may take a hit if you are late on bills like utilities, rent, or car payments.
It helps if your bills get paid without you thinking about it. Consider setting up pre-authorized payments (known as direct debits in the UK, Ireland and Australia) through your bank. Many Canadian banks, such as Scotiabank, allow you to set up electronic bill payments so that you never miss a payment.
Consistently on-time payments can indicate you’re a low-risk borrower. This can lead to better financial opportunities.
4. Not Reading Terms and Conditions
Always read and understand the terms and conditions of contracts like cell phones, insurance, banking products, or the lease agreement with your landlord. Failure to adhere to these terms may result in unforeseen penalties and expenses. Take your time to make informed decisions and avoid being rushed or pressured into agreements.
5. Carrying Credit Card Debt
While credit cards can be useful for building credit, they can become problematic if misused. Accumulating high levels of debt due to overspending can undermine your financial goals. To avoid this, pay off your credit card balance in full each month and avoid late payments. Also, limit yourself to one or two cards for expenses you can manage.
6. Not Filing Your Taxes
Most people living in Canada should file taxes every year by April 30, even if they had little or no income.
You’ll need a Social Insurance Number (SIN), similar to a National Insurance number in the UK, a PPS number in Ireland, a Tax File Number in Australia or a PAN in India. Not filing can mean missing government benefits, such as the GST/HST credit and the Canada Child Benefit, and paying penalties or interest if you owe tax.
7. Not Budgeting Properly for Your Move
Moving costs money. International moves can be particularly costly. You will incur many expenses, including shipping, insurance, duty, taxes, visa fees, and exchange rates and transfer fees when you move your savings to Canada. You need to budget well for these costs. Make sure your budget includes all possible expenses so you start your Canadian journey on the right financial footing.
8. Not Asking Questions
You may not even know what you don’t know. So, don’t hesitate to seek professional advice. Canadian banks like Scotiabank offer comprehensive financial planning services and multilingual support. Their advisors can help you understand your financial options, create a personalized budget, and guide you towards financial success. Book an appointment with a Scotiabank advisor.
Lastly, planning your financial journey in Canada should begin before you arrive. Early financial planning and learning about your banking options will set you up for success. While adapting to a new country may be challenging, starting right can make the transition smoother and help you achieve your goals.
Legal Disclaimer
About the author